








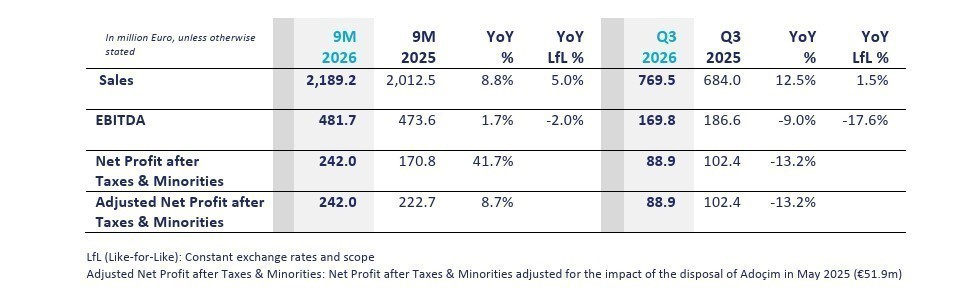
Nine-month sales grew 9% (+5% LfL), with Q3 sales up 13% (+2% LfL), reflecting broad-based organic growth across all regions and a positive contribution from recent acquisitions.
Nine-month EBITDA up 2% to €482m, (-2% LfL), with growth in Greece, Southeastern Europe and Eastern Mediterranean. Increased cost-saving initiatives under Project Prime helped partially offset higher energy and raw materials costs. Profitability in the US was also affected by one-off events, such as the extended outage at Pennsuco and the unplanned outage at Roanoke, adverse weather and softer residential demand & unrealized price increases particularly in Florida. Q3 EBITDA reached €170m.
Nine-month Net Profit at €242m, up 42% (+9% adjusted after the 2025 divestment). Q3 net profit at €89m. • S&P upgraded TITAN to Investment Grade, reflecting the Group’s strong balance sheet and financial discipline. Leverage remained healthy at 1.56x.
Nine-month CapEx of €248m, in line with the TITAN Forward strategy, focused on growth and efficiency projects, including the expansion of portable ready-mix plants serving data centers, capacity expansion in fly ash and aggregates, captive power generation in Türkiye and dedicated cement export silos in Egypt.
Integration of the 3 recent acquisitions, representing c.€700m of investment YTD, is progressing well, with synergies and operational improvements on track to deliver c. €60m by 2029. EBITDA contribution is expected to grow from c.€28m YTD to c.€45m in FY26 and over €100m by 2029.
Large projects continue to progress: the construction of a second production line at Traçim in Türkiye, the calcined clay project in Virginia and the iFESTOS CCS project in Athens, Greece, under assessment.
Continuous positive developments in ESG ratings with the Board approving new ESG targets for 2030, setting the Group’s sustainability priorities for the years ahead.
Titan 2026 Outlook
High-single-digit growth expected in sales and mid-single-digit growth in EBITDA, supported by the launch of PRIME, TITAN’s cost and efficiency program, and the contribution from recent acquisitions.
Full-year CapEx expected at c. €300m.
Marcel Cobuz, Chair of the Group Executive Committee: “Our growth continued in the first nine months despite inflationary pressures and one-off events. Supported by growth investments and the integration of recent acquisitions, we are building a stronger TITAN and accelerating the delivery of Forward 2029 strategy.”
John Ioannou, Group CFO: “The strong nine-month results and our new investment-grade status reflect TITAN’s financial strength and discipline, while self-help measures under Project Prime continue to support our profitability. Looking ahead, we remain optimistic and are well positioned to deliver another record year.”
Outlook
The global economy is expected to remain resilient throughout the remainder of 2026 despite geopolitical uncertainty, elevated energy costs and higher financing costs. Infrastructure renewal, energy security and housing needs continue to support activity across most of TITAN’s markets.
The US economy is expected to maintain moderate growth through the remainder of 2026. Construction demand is likely to remain differentiated, with public infrastructure spending and data-center investments continuing to support activity, while elevated borrowing costs and affordability constraints weigh on residential construction. In the MidAtlantic, infrastructure projects and data-center developments should support a more diversified demand environment, while in Florida, residential market weakness is expected to constrain overall construction momentum. While near-term conditions remain mixed, longer-term infrastructure renewal and digital-investment trends continue to support TITAN’s North American markets. The Greek economy is expected to remain resilient through the remainder of 2026, supported by investment activity, EU funding and a strong labor market. Infrastructure investment is expected to remain the main driver of construction demand, complemented by selected commercial developments and stable residential activity. Energy-efficiency programs provide additional opportunities and investments in tourism support commercial construction. Across Southeastern Europe, economic activity should remain broadly resilient for the rest of 2026, supported by domestic demand and investment. Construction activity should continue to benefit from residential development, tourism-related projects and infrastructure spending, although energy costs, financing conditions and project execution remain important factors. Albania and Kosovo are expected to remain supported by residential and tourism-related activity, Serbia by infrastructure investment and preparations for EXPO 2027, North Macedonia by transport infrastructure projects, and Bulgaria by residential construction and EU-supported public investment. Economic activity in the Eastern Mediterranean is expected to remain supportive for the balance of 2026, despite ongoing geopolitical uncertainty. In Egypt, services, tourism and investment are expected to support demand, while housing needs, hospitality projects and energy investments provide opportunities. In Türkiye, residential construction should benefit from housing needs, urban renewal and post-earthquake rebuilding, while transport infrastructure remains the key driver of construction activity. The Group is also progressing strategic investments, including the solar park (JV – to be completed by the end of the first quarter of 2027) and silo expansion at Traçim, supporting the kiln investment, for which the required license is already in place.
TITAN remains focused on disciplined execution of its Forward 2029 Strategy, strengthening its core businesses and expanding its alternative cementitious materials platform through targeted investments and partnerships, while advancing operational excellence, digitalization and low-carbon innovation to deliver sustainable long-term value. For 2026, TITAN expects High single-digit growth in sales and mid-single-digit growth in EBITDA, supported by resilient demand, improved pricing, the benefits of TITAN’s Project on costs and efficiencies “Prime” and the contribution from recent acquisitions, despite a significantly higher cost environment and the one-off costs incurred earlier in the year. CapEx for 2026 is expected at approximately €300m, supporting targeted growth and efficiency projects across the Group.
TODAY's NEWS
- METLEN: Record Revenue of €6.2 Billion in the First Nine Months – Reaffirms 2026 EBITDA Target of Up to €1.15 Billion
- PPC Group: Kotsovolos Acquires 100% of Romanian Retailer Flanco for €35 Million
- Alter Ego Media: TP ICAP Sets €8.30 Price Target with a “Buy” Rating
- Deutsche Bank: Athens Stock Exchange gains 26.3% in first 10 months, outperforming Wall Street and European markets


